Wednesday, 15 February 2017

Tax Benefits of Home Loan

Use the interactive House Loan EMI Calculator to calculate your house loan EMI. Get all details on interest payable and tenure using the home loan calculator.

 House Loan

Monday, 13 February 2017

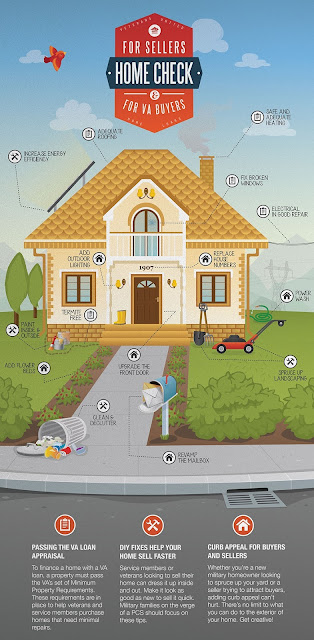
For seller home check for VA buyers

Loan For Home Construction - Go with HDFC home construction loan and you can build your home your ways. Visit us to know more about HDFC construction loan.

 Loan For Home

Friday, 10 February 2017

Should you invest your money or use it to prepay home loan?

If you have an outstanding home loan, and happen to have just received an annual bonus or any other lump sum payment, should you use it to prepay your loan? Or, should you invest it to meet some other goals? Assess the following conditions to arrive at the right decision.

The first variable to be considered is psyche: some people may not be comfortable with a large housing loan and to reduce their stress they may want to get rid of the loan burden at the earliest. For them, settling the question of how to use their bonus is simple: just pay off the loan. Gaurav Mashruwala, Sebi-registered investment adviser, categorically states: "You should pay off the home loan at the earliest. Several unfortunate happenings— job loss, death of the earning member, serious illness, etc—can cause trouble during the 10-15 year loan period. Treat it as a mind game and not a numbers game."

Tax benefit is the next variable. If a home loan does not seem like the sword of Damocles hanging over your head, it makes sense to continue with the regular EMI schedule. This is because of the tax benefits that a home loan offers. The principal component of the EMI is treated as investment under Section 80C. The interest component is also deducted from your taxable income under Section 24. The annual deduction in respect of the interest component of a housing loan, for a self occupied house, is limited to Rs 2 lakh per annum.

You won't be able to claim deduction on interest paid above Rs 2 lakh. So, if your annual interest outgo is higher than Rs 2 lakh, it makes sense to prepay the loan, and save on future interest payment. For example, the annual interest on a Rs 70 lakh outstanding loan, at 9.5%, comes out to be Rs 6.65 lakh. After taking into account the Rs 2 lakh deduction under Section 24C, the interest component will fall to Rs 4.65 lakh, and bring down the effective cost of interest from 9.5% to 8.64%, even for the people in the 30% tax bracket.

You can, however, optimize the tax benefits if the loan has been taken jointly, say, with your spouse. "If joint holders share the EMIs, both can claim Rs 2 lakh each in interest deduction," says Harsh Roongta, Sebi-registered investment adviser. In case of joint holders, there is no need to prepay if the outstanding amount is less than Rs 40 lakh.

There is no cap on deduction in lieu of interest paid on home loan, if the property is not self-occupied. "Since there is no cap for interest on loan against second or rented out homes, there is no need to prepay it," says Naveen Kukreja, CEO and Co-founder, Paisa Bazaar. Bear in mind, by prepaying your loan, you may also forego future tax benefits. For instance, if by prepayment, you bring down your outstanding loan amount to Rs 20 lakh, your annual interest outgo for subsequent years may fall below Rs 2 lakh. Thus, you won't be able to avail of the entire tax-deductible limit and, in such a scenario; prepayment may not be a good strategy. Also, building an emergency fund, if you don't have one, should take a priority over prepaying the housing loan: "Make sure that you have a contingency fund in place before opt for prepaying your home loan.

The third key variable is returns from investment of the lump sum at hand. As a thumb rule, you should go for investment, instead of prepayment, only when the post-tax return from the investment is likely to be higher than the effective cost of the housing loan. For investors in the 30% tax bracket, and whose outstanding home loan balance is less than Rs 20 lakh, the effective cost of loan is only 6.65%. Since there are several risk-free, tax-free debt options such as PPF, Sukanya Samruddhi Yojana and listed tax-free bonds, which offer higher annualized return than this, it makes sense to invest in them.

All the debt products mentioned above are long-duration products. If your risk-taking ability is higher and time horizon is longer, you can consider investing in equities, which can generate better returns "It's sensible for long-term investors (five year-plus holding period) to go for equities, provided they are savvy and understand the risks involved there.

There are some home loan products that provide an overdraft facility of sorts and help you maintain liquidity. All you have to do is to park the surplus money in these products and not bother with whether it's a prepayment or not. It's like prepayment with the option of taking out that money, in case you need it in future for personal use or for investment purpose. The strategy of maintaining the housing loan interest close to Rs 2 lakh per annum can also be managed by these special loan products. And even if you are going to invest, the SIPs can go from this account.

"I park my bonus and do SIPs in equity from the loan account," says Kukreja. Most banks charge more for these special loan products. "Though the stack rate differential is more, you can bring it down by bargaining with the banks.


{Source: http://economictimes.indiatimes.com/wealth/plan/should-you-invest-your-money-or-use-it-to-prepay-home-loan/articleshow/52161038.cms}

Tuesday, 7 February 2017

HOME LOAN CALCULATOR TO GAIN TAX BENEFITS

As per the provisions of income tax act you can claim exemption for the repayment of interest as well as principal. But there are certain limits to get exemption for interest and principal repayment. To know your tax exemption on home loan repayment you need to first understand how interest is calculated, and that’s where Quicko’s Home Loan Interest Calculator comes into the picture. Following is the illustration showing two components of your EMI i.e. interest and principal.

How does this Home Loan Calculator Work?
Praveen’s yearly income is Rs.10, 00,000. His age is 30 years. He is purchasing a house worth Rs.50, 00,000 and availed a loan for Rs.40, 00,000. Loan tenure is 15 years and interest rate is 10.5%. Following is his loan repayment/amortization schedule.

From this schedule, in our Home Loan Interest Calculator we can see that for initial years major component of EMI is interest and payment towards principal is very little. The graphical presentation of the same data shows interest as well as principal payment due after every year. The next column in the table after interest column shows your tax savings every year based on your income slab. While calculating tax benefit, growth in your income at 3.5% per annum is considered.

If we look at the total amount for interest we can see that, at current interest rate for 15 years you end up paying as much interest as your borrowing amount. If you increase the tenure, total interest payment increases.

Let’s understand how this repayment schedule is prepared in this Home Loan Interest Calculator. On your first EMI payment interest on your borrowing is calculated for one month. This interest amount is deducted from EMI. The difference is considered as your payment towards principal. So for the next month interest is calculated on your reduced principal due after last month’s payment towards principal.

One can pay more than the EMI or can pay a lump sum whenever they have excess income or saving to reduce the interest payment. The amount you pay beyond your EMIs goes towards the repayment of principal amount and it reduces interest outgo in subsequent payments.

{Source: https://quicko.com/blog/tax-benefit-home-loan-calculator/}

Monday, 6 February 2017

Qualifying for a VA Home Loan

Use the interactive home loan EMI calculator to calculate your home loan EMI. Get all details on interest payable and tenure using the home loan calculator.

 Home Loan

Friday, 3 February 2017

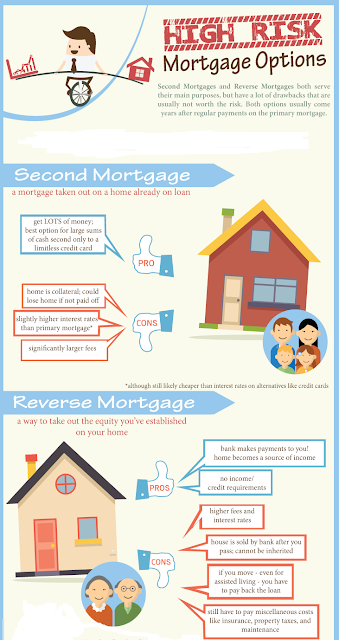
High Risk Mortgage Options

Use the interactive house loan EMI calculator to calculate your home loan EMI. Get all details on interest payable and tenure using the home loan calculator.

 House Loan

Wednesday, 1 February 2017

What You Would Be Informed On Using It Primary House Loan

The majority even think of the actual dwelling that they're going to invest in. It's quite with the shed weight package plus scam for several years to obtain the actual dwelling how they really want. People simply just want a dwelling and tend to be more concerned with related to choosing a dwelling that matches their whole spending plan.

No matter whether waiting to buy your goal dwelling or simply no matter whether you pay for a major step dwelling, purchasing dwelling has become the most important conclusions that you're going to generate you know. Lots of people prefer to get hold of a dwelling which can be suitable within their cultural formed. They are only going to think about getting dwelling within the several spaces or stuck in a job several progressions.

Yet, just about anybody it can often be for you to achieve house loan to match your seen cultural formed. Still, will possibly not be capable to essentially supply the dwelling, despite the fact that obtain house loan. Keep in mind your individual house loan can never be much more than 35% with people whole profits. Quite a few industry experts acknowledge quite possibly the following amount of money can be excessively huge. In truth, usually there are some personal industry experts of which declare that your individual home loan repayments ought not are much more than 25% from your accumulate give.

Just about anybody, it can often be difficult to find a real house loan in the modern current economic climate. Electrical power different types of business loans on the market. Yet, you'll wish loans by using a curiosity amount. The fewer the attention amount, the exact a lower cost to implement it that will acquire the funds may for your personal house loan. A very few fraction tips can produce a number of variance taking into consideration who's normally requires a few a long time for the regular mortgage loan.

Naturally, it is attainable that will re-finance your household within the foreseeable future and find an even better credit ratings. You should never stress but if your par is tiny bit over you like! You can acquire finance at a loan company or simply at a bank industry experts house loan. To read more for a lot of these destinations, can be done an online seek out.

One can find bodies which have been manufactured to help people by using poor or simply compared to other personal challenges. Assuming you have functioned during the military services, you will acquire an exceptional mortgage loan fashioned mainly for military services experienced persons. Prior to towards loan company to locate the mortgage loan, you must have some records if you wish. Your individual bank is able to provide a directory of records that you're going to really need to accomplish the money practice.

{Source: http://fashionable-exciting-sparkling.blogspot.in/2014/04/what-you-would-be-informed-on-using-it.html}